Set the household allocation
Match stocks, bonds, and cash to the money's purpose, timeline, spending needs, and the household's ability to absorb loss.
Flat-fee investment management
Your portfolio should have a job, a process you can understand, and a price that does not climb automatically with the account balance. Flames FP includes investment management inside a fixed quarterly membership.
Direct answer
Every Flames FP membership includes professionally designed model portfolios, monitoring, rebalancing, and supported investment-account management through Altruist. There is no minimum investment balance and no separate percentage-of-assets fee. The appropriate membership depends on how much financial-planning coordination your household needs.
The work
Investment management starts by deciding what each part of the portfolio is meant to fund. The implementation should follow that purpose, not a market forecast or a stack of unrelated holdings.
Match stocks, bonds, and cash to the money's purpose, timeline, spending needs, and the household's ability to absorb loss.
Support eligible account opening and transfers, implement the selected model portfolios, and keep the account structure understandable.
Review allocation drift and household changes, then rebalance when the portfolio or financial plan calls for it—not simply to create activity.
The decisions around the investments
A portfolio recommendation is more useful when it accounts for the decisions happening around it. The amount of coordination depends on the membership and the household's circumstances.
Consider account type, tax lots, potential gains and losses, charitable plans, and the reason for the trade before changing taxable holdings.
A workplace plan, HSA, inherited account, or spouse's plan may sit elsewhere and can still inform the household allocation and risk discussion.
A large employer-stock position needs more than a target allocation. It may require a deliberate sale, tax, and reinvestment sequence.
The price
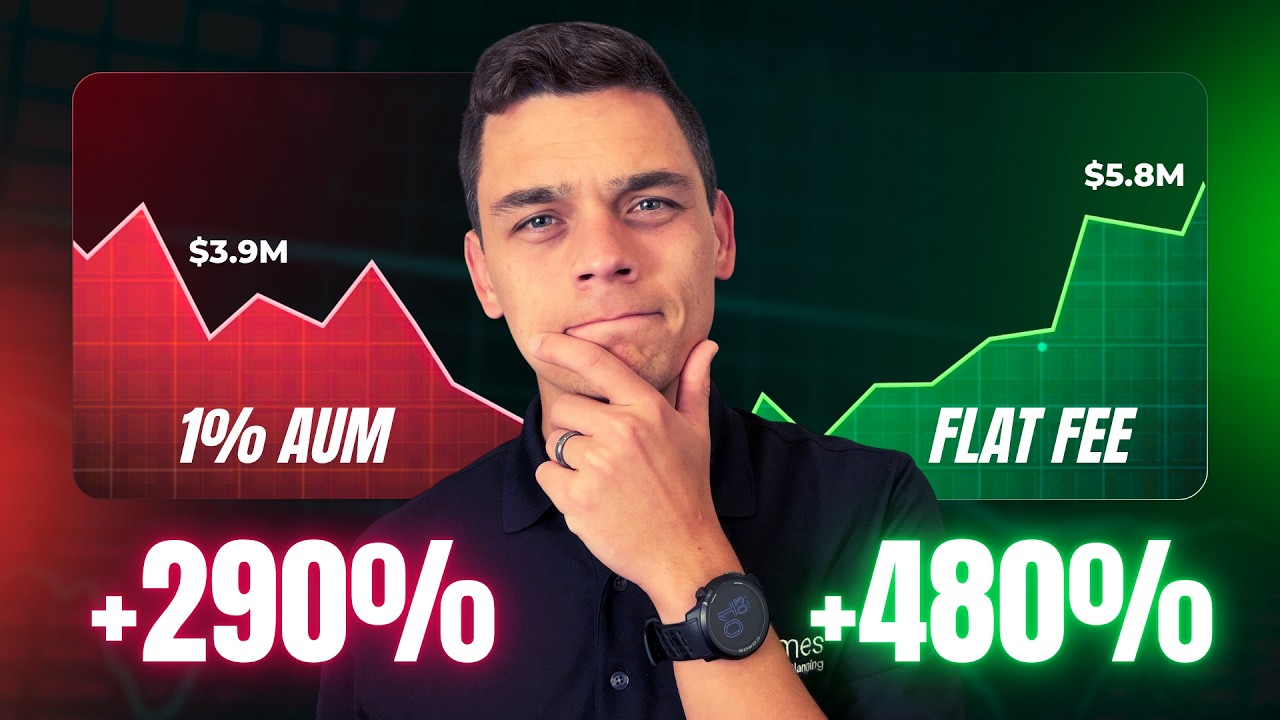
Flames FP uses fixed quarterly membership pricing. The membership is based on the planning relationship—not simply the number of dollars in an investment account.
There is no separate advisory charge equal to 1%—or another percentage—of the assets managed through the relationship.
Investment management is included in the membership fee instead of appearing as an additional portfolio-level charge.
Broader tax, retirement, estate, or equity-compensation needs may call for a broader membership. Market growth alone does not automatically increase the fee.
Watch and learn
Start with three videos selected for this page, then use the controls to explore every published Flames FP video guide.
Videos 1–3 of 14
Common questions
Yes. Every membership includes professionally designed model portfolios, monitoring, rebalancing, and supported investment-account management through Altruist.
No. Investment management is included in the fixed quarterly membership fee, with no additional AUM percentage fee and no minimum investment balance.
Flames FP supports investment-account management through Altruist. Account eligibility, transfer details, and the appropriate setup are confirmed during onboarding.
Not necessarily. Existing holdings, account types, embedded gains, transition costs, and near-term cash needs should be reviewed before changes are made. The appropriate pace depends on the account and the household's circumstances.
Yes. Workplace plans and other outside accounts can be considered when setting the household allocation, even when Flames FP does not directly manage the account. Direct-management availability depends on the account and plan access.
Account location, potential gains and losses, tax lots, charitable giving, withdrawals, and retirement-tax considerations can be evaluated before portfolio changes. The specific tax-planning work depends on the membership and household circumstances.
Yes. A concentrated position can be evaluated alongside future vesting, tax lots, diversification priorities, cash needs, and the rest of the portfolio. The resulting strategy may involve a multi-year transition or a faster reduction when concentration risk is more urgent.
No. Investment management is included inside a Flames FP membership so the portfolio can connect to the level of financial-planning work selected by the household.
No. Diversification, monitoring, and rebalancing do not guarantee returns or prevent losses. The goal is to use a repeatable process that matches portfolio risk to the household's plan.
Next step
Schedule a discovery meeting to discuss your current accounts, employer stock, annual advisory cost, and the planning work you want connected to the portfolio.